
As we navigate the complex landscape of non-profit organizations, one entity stands out for its unique blend of social responsibility and economic viability: the social cooperative. But what exactly is a social cooperative, and how does the law govern their operations? In this article, we’ll delve into the world of social cooperatives, exploring their history, structure, membership, tax benefits, and legislation.
What are Social Cooperatives?
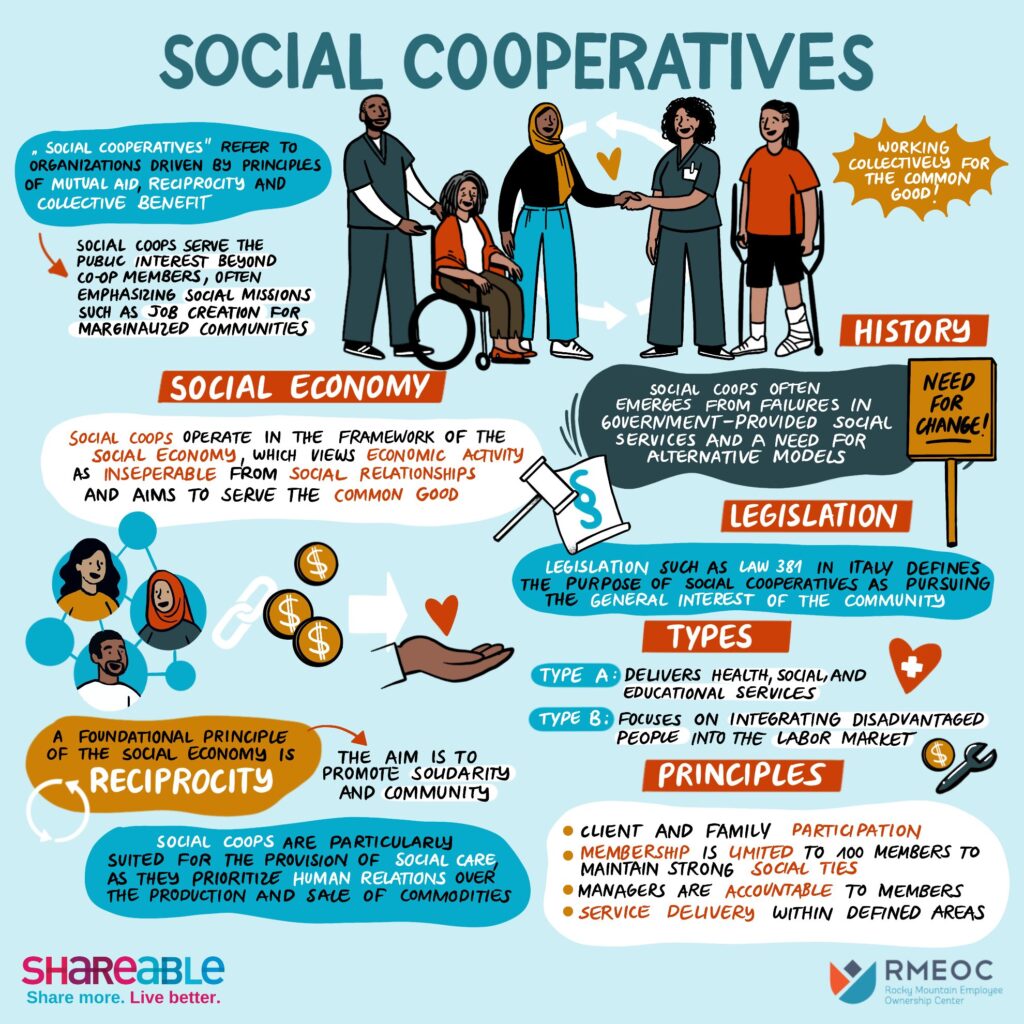
A social cooperative is a specific form of legal entity designed to promote objectives that benefit the broader community. These organizations focus on integrating social citizens, providing healthcare and educational services, and fostering employment opportunities for disadvantaged individuals. Think of them as a hybrid between a business and a non-profit organization.
The History of Social Cooperatives
Social cooperatives have their roots in the 19th century, when philosophers like Robert Owen and Charles Fourier advocated for cooperative economics. Over time, these ideas evolved into modern-day social cooperatives, which now operate globally.
Types of Social Cooperatives
There are two primary types of social cooperatives: those that manage services (type A) and those that engage in diverse activities (type B). The latter can include worker-owners with disabilities, who make up a crucial part of the cooperative’s membership.
Membership Structure
Within a social cooperative, membership is composed of various types of individuals:
- Workers who exchange their work activity for remuneration
- Beneficiaries who use the cooperative’s services directly or indirectly
- Investors who prioritize financial returns over mutualistic benefits
- Volunteers who provide their work activity gratuitously in exchange for solidarity
Worker-Member and Member-Owner Roles
Worker-members are essential to the functioning of social cooperatives, as they contribute labor and expertise to generate revenue. In contrast, member-owners play a vital role in decision-making processes, providing financial support, and overseeing the cooperative’s operations.
Pension and Compensation Systems
Social cooperatives have a pension system that reduces compulsory social security contributions for disabled worker-members. This benefits not only these members but also encourages other workers to participate, fostering an inclusive work environment.
Tax Benefits: Previdenziali Benefits
One of the key advantages of social cooperatives is the previdenziali benefit, which enables them to offer a pension system that reduces compulsory social security contributions for disabled worker-members. This system promotes economic sustainability while ensuring that members receive fair compensation for their labor.
Taxation and Financial Management
Social cooperatives enjoy several tax benefits, including:
- Prohibition on distributing dividends above a certain threshold
- Limitation on remuneration of financial instruments offered to cooperator members
- Obligation to transfer social patrimony to mutualist funds upon dissolution
These measures ensure that the cooperative’s resources are allocated efficiently, promoting long-term sustainability.
Income Exemption and Remuneration
Social cooperatives can benefit from an income exemption for worker-members who provide continuous work. This allows the cooperative to maintain a healthy financial situation while ensuring fair compensation for its members.
The deductibility of remuneration up to a certain level is another significant advantage, providing a safety net for workers and promoting economic stability within the cooperative.
IRAP Benefits
Social cooperatives that perform diverse activities aimed at integrating people with disabilities into employment can deduce the cost of work for such persons from their base income. Alternatively, social cooperatives operating socio-sanitary and educational services can obtain recognition of reduced IRAP rates or exemption from the tax itself on a regional basis.
International Cooperation
Social cooperatives have gained international recognition, and many countries offer specific incentives to support their development. International cooperation has enabled these organizations to share knowledge, expertise, and resources, promoting global social responsibility.
Case Study: Cooperativa Italiana del Cibo (CIC)
Cooperativa Italiana del Cibo (CIC) is a well-known social cooperative in Italy that promotes food security and sustainable agriculture. Founded in 1985, CIC has become a model for social cooperatives worldwide, demonstrating the effectiveness of cooperative economics in achieving social and environmental objectives.
Conclusion
In conclusion, social cooperatives are unique entities that navigate the complexities of non-profit organizations while promoting economic viability. By understanding their history, structure, membership, tax benefits, and legislation, we can appreciate the significance of these organizations in shaping our society.
Frequently Asked Questions (FAQs)
A: A social cooperative is a specific form of legal entity that promotes objectives benefiting the broader community through integrating social citizens, providing healthcare and educational services, and fostering employment opportunities for disadvantaged individuals.
A: Social cooperatives can operate in one of two activities (management of services or diverse activities), but not both. An exception is made when the two activities are functionally linked, requiring strict separation.
A: Social cooperatives have various types of members, including workers who exchange their work activity for remuneration, beneficiaries who use the cooperative’s services directly or indirectly, investors who prioritize financial returns over mutualistic benefits, and volunteers who provide their work activity gratuitously in exchange for solidarity.
A: Social cooperatives enjoy several tax benefits, including previdenziali benefits, prohibition on distributing dividends above a certain threshold, limitation on remuneration of financial instruments offered to cooperator members, and obligation to transfer social patrimony to mutualist funds upon dissolution.
A: Yes, for social cooperatives, the income from worker-members who provide continuous work does not exceed 50% of all other costs (excluding raw materials and supplies).
Q: What is the purpose of deductibility of remuneration?
A: Production and labor cooperatives can benefit from deductibility of sums paid to worker-members as an integration of remuneration up to a certain level.
A: Yes, social cooperatives that perform diverse activities aimed at integrating people with disabilities into employment may deduce the cost of work for such persons from their base income. Alternatively, social cooperatives operating socio-sanitary and educational services can obtain recognition of reduced IRAP rates or exemption from the tax itself on a regional basis.
A: Social cooperatives play a vital role in promoting objectives that benefit the broader community through integrating social citizens, providing healthcare and educational services, and fostering employment opportunities for disadvantaged individuals.


